
7 Key Steps in a Comparative Market Analysis for Nevada Properties
1. Define the Subject Property
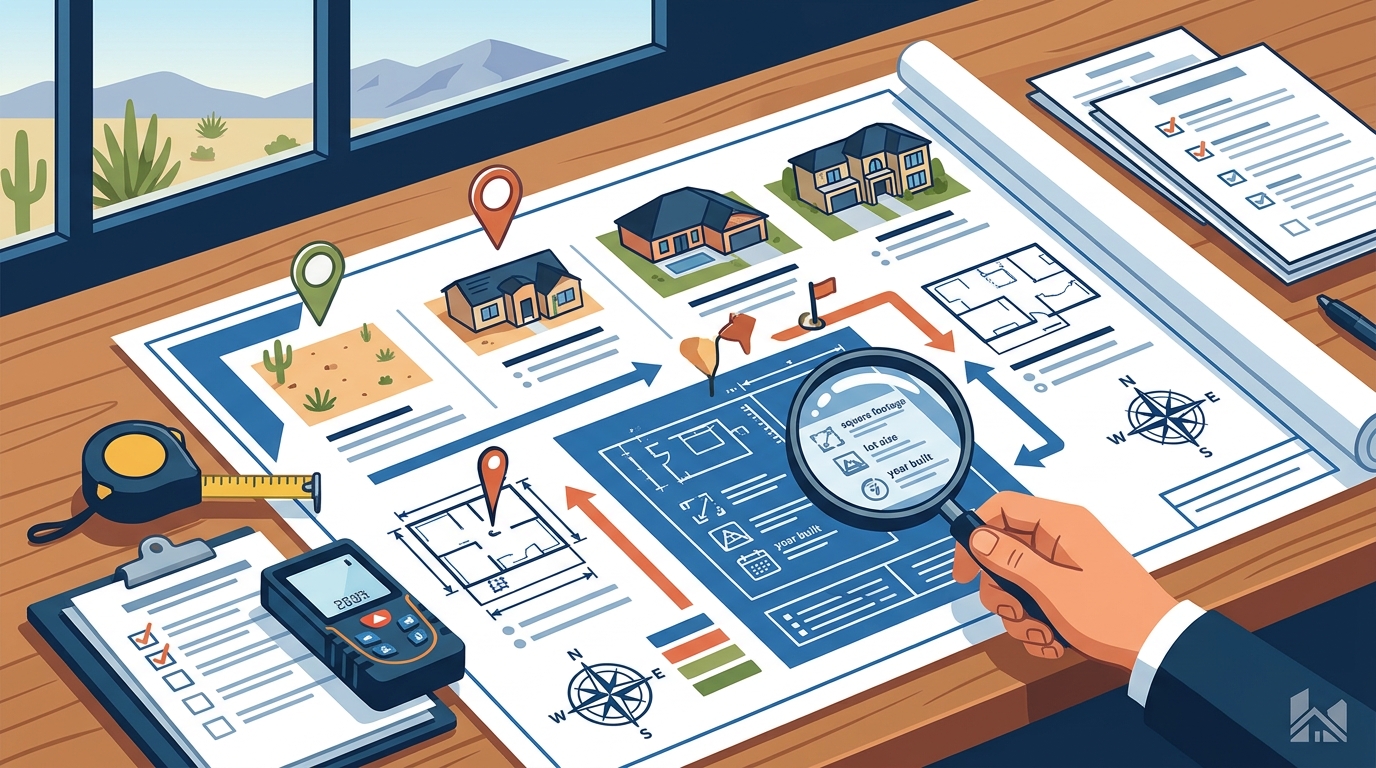
Accurate valuation begins with a precise inventory of the home's physical and legal characteristics. The first step is to document the subject property's specific attributes, including square footage, lot size, year built, and architectural style. This baseline ensures that any comparisons made later are relevant and fair. In Nevada, where property types range from desert lots to luxury estates, this definition is critical for setting the scope of the analysis. For additional details, review the Frequently Asked Questions.
2. Identify the Target Market Area
Narrowing the geographic scope ensures that comparisons reflect local buyer behavior and pricing norms. A CMA is only as good as the geographic boundaries used to select comparables. Agents typically define a target area based on school districts, neighborhood boundaries, or a specific radius around the subject property. In Nevada, market conditions can vary significantly between different parts of the same city, so this step requires careful local knowledge. For additional details, review the About.
3. Select Comparable Properties
Choosing the right comparable sales is the most critical step in the entire process. A comparable property, or comp, is a home that is similar to the subject property in size, condition, and location. Ideally, comps should have sold within the last three to six months to reflect current market conditions. Allen Zeller focuses on selecting comps that are as similar as possible to the subject property to minimize the need for large adjustments. according to Miami Dade Comparable
4. Analyze Active and Pending Listings
Reviewing current inventory helps identify direct competition and potential pricing pressure. Active listings are homes currently on the market, while pending listings are those under contract but not yet closed. By analyzing these properties, an agent can gauge how long similar homes are taking to sell and what price points are attracting buyers. This data helps sellers understand the level of competition they will face when listing their property. according to Marketing Research Basics
5. Adjust for Property Differences
Adjustments account for differences in features, condition, and market timing between the subject and the comps. No two homes are identical, so adjustments are made to the sale prices of the comps to reflect differences in square footage, number of bathrooms, garage size, and overall condition. For example, if a comp has a renovated kitchen and the subject property does not, a negative adjustment is applied to the comp's price. This step requires professional judgment to ensure the adjustments are reasonable and supported by market data.
6. Review Market Trends and Absorption Rates
Understanding the pace of the market helps determine if a property is likely to sell quickly or sit on the market. The absorption rate is the number of months it would take to sell all currently listed homes at the current sales pace. In a seller's market, where absorption rates are low, properties may sell above asking price. In a buyer's market, where absorption rates are high, sellers may need to price more aggressively. Allen Zeller monitors these trends closely to advise clients on the best timing for their transaction.
7. Finalize the Price Range
Choosing the Right Approach
When selecting a CMA, look for an agent who provides a detailed breakdown of the comps used and the rationale behind each adjustment. A good CMA is not just a list of prices; it is a narrative that explains how the market is behaving and how your property fits into that landscape. Allen Zeller provides this level of detail to ensure clients make informed decisions about their real estate goals.
Frequently Asked Questions
What is the difference between a CMA and an appraisal?
A CMA is an estimate of value prepared by a real estate agent, while an appraisal is a formal valuation prepared by a licensed appraiser. Appraisals are typically required by lenders for mortgage underwriting, whereas CMAs are used for pricing and marketing purposes.
How many comparable properties should be used in a CMA?
Most CMAs use between three and six comparable sales. Using too few comps can lead to an inaccurate estimate, while using too many can dilute the relevance of the data. The goal is to find a balance between quantity and quality.
How often should a CMA be updated?
CMAs should be updated at least every three months, or more frequently if the market is changing rapidly. In volatile markets, monthly updates may be necessary to ensure the pricing strategy remains relevant.
Can a CMA be used for estate planning or divorce proceedings?
While a CMA can provide a useful estimate, it is generally not accepted as a formal valuation in legal proceedings. For estate planning or divorce, a certified appraisal is usually required to meet legal and financial standards. Learn more: allenzeller com.